Harish joined the Business Development team at Integrum ESG after having previously overseen BD for the investment network Venture Giants, and also worked within the Customer Experience Program Team at Amazon. He has a BSc in Philosophy, Logic and Scientific Method from the London School of Economics and Political Science.
The FCA has simplified climate reporting for UK investment firms. This guide explains what has changed, what it means for your reporting and what to do next.
The FCA's TCFD rules apply to asset managers, including wealth managers running discretionary portfolios, and to FCA-regulated asset owners such as life insurers and pension providers.
Firms are in scope where assets under management or administration exceed £5bn.
Short on time? Speak to our team about your TCFD reporting plans for 2027.
On 25 September 2026 the FCA confirmed a simpler set of climate reporting rules for investment products, published in Handbook Notice 144. The main changes are:
The firm-wide TCFD entity report is unchanged. The FCA has said it will continue to consider how to streamline the entity-level rules and will give an update later.
The FCA's 2025 review of climate reporting found that product reports were often too complex for retail investors and not widely used. The FCA estimates the changes will save the 295 firms in scope around £20m a year.
When the proposals were published in June 2026, Michelle Beck, director of wholesale buy-side at the FCA, said the regulator was "cutting complexity in our rules for asset managers".
For most firms, climate reporting continues in a different shape.
The firm-wide report remains, and it relies on the same fund-level data that fed the old product reports.
The FCA's own cost analysis treats third-party Scope 1, 2 and 3 emissions data as an ongoing cost for asset managers, and consultation respondents noted that firms will still need climate-relevant data, systems and processes to answer client requests.
Firms in scope must still publish a TCFD entity report by 30 June each year. No changes have been made to this process.
It explains how the firm manages climate risk across the assets it looks after, under the TCFD headings of governance, strategy, risk management and metrics and targets. In practice the report covers:
The first two figures are built up fund by fund. Firm-wide emissions come from the holdings in each fund and portfolio, and WACI is expected for each fund or strategy.
Firms therefore still need emissions data for every fund and portfolio in scope, even though they no longer publish a report for each one.
WACI is a portfolio's average carbon intensity: each company's emissions per $1m of revenue, weighted by its size in the portfolio. The emissions and WACI expectations come from the TCFD's guidance for asset managers and asset owners, which the FCA's rules in chapter 2 of its ESG sourcebook require firms to reflect.
The figures also need to be current. Under ESG 2.1.8R, firms must "insofar as is reasonably practicable, use the most up to date information available". Fixing holdings at 31 December is common practice. Using company emissions data frozen at that date, when newer disclosures are available by the time the report is prepared, is harder to justify.
For products offered to retail investors, firms must check regularly whether climate risk could materially affect performance.
Where it could, they must say so in the risk information they already provide, such as a product summary under the Consumer Composite Investments regime.
The check can form part of a firm's existing risk process, and firms do not need to explain why a risk is not material.
The FCA has also confirmed that firms may use sustainability-related terms in these disclosures under the SDR naming and marketing rules.
From 30 June 2027, institutional clients can ask for each product's Scope 1, 2 and 3 emissions once a year, where they need it for their own climate reporting.
Where practicable and allowed by the firm's data contracts, firms should also provide other climate data the client reasonably needs, and state how much of it is verified, reported, estimated or unavailable. Responses should come within a reasonable time, in a sensible format and with context on how to read the figures and their limits.
Many of these clients have reporting duties of their own. Pension scheme trustees, for example, must calculate four climate metrics, including a portfolio alignment metric.
They report on their own timetables, and asset owners responding to the FCA's consultation said they often engage with managers more than once a year to get information.
"Rather than issue a one-size-fits-all fund-level report, an asset manager may need to respond to queries for numbers such as CO2e footprint, WACI and Implied Temperature Rise from different investors and at different points in the year," says Shai Hill, CEO of Integrum ESG.
"So the annual TCFD migraine may be over. The occasional, less predictable headache may not be."
Firms that license emissions data from a third party should check that their contracts allow them to publish it in the entity report and share it with clients.
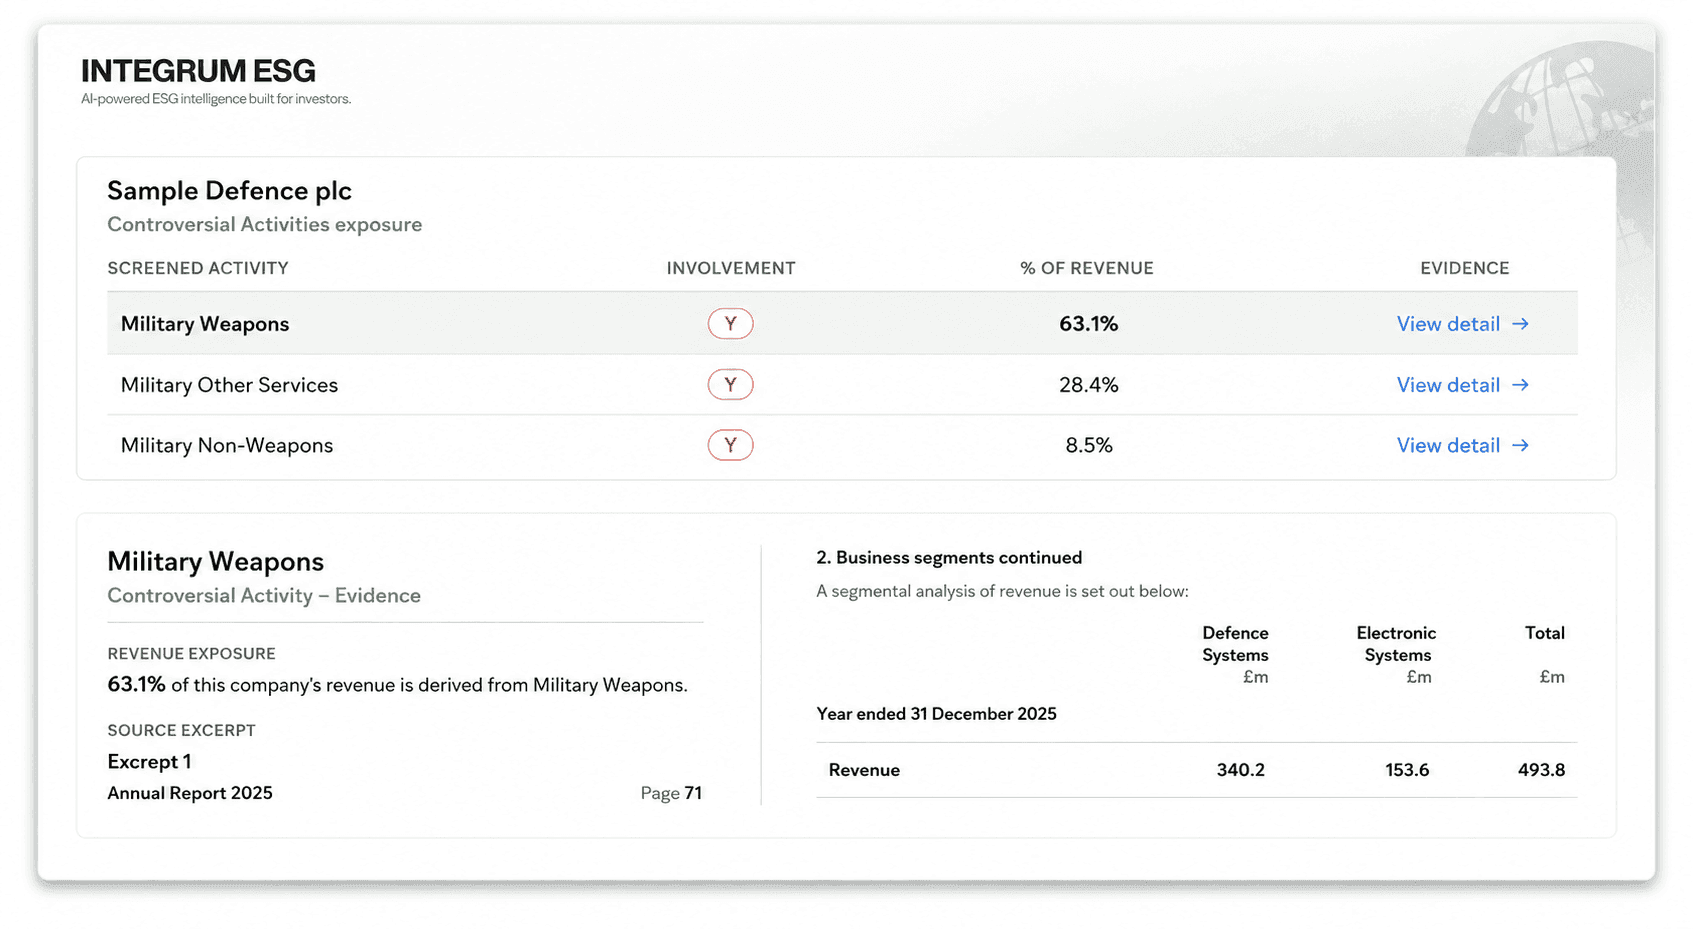
For the underlying data, Integrum ESG's climate risk data is updated within 10 days of company disclosure, with every datapoint dated and traceable to source.
Integrum ESG's TCFD reporting feature produces portfolio climate metrics from a single holdings upload, as at any date the firm chooses. For each portfolio the Platform provides:
For definitions of each metric, see our Guide to TCFD Reporting for Investors.
To follow climate disclosure rules across jurisdictions, see Integrum ESG's Regulatory Intelligence solution.
Browse frequently asked questions about the platform.
Can’t find the answer you’re looking for? Please get in touch with our team.