Harish joined the Business Development team at Integrum ESG after having previously overseen BD for the investment network Venture Giants, and also worked within the Customer Experience Program Team at Amazon. He has a BSc in Philosophy, Logic and Scientific Method from the London School of Economics and Political Science.
An up-to-date guide on California’s climate disclosure rules, what they require and why they matter for global asset managers and hedge funds. All future regulatory updates and amendments will be summarised at the end of this article.
California has enacted two key pieces of legislation - SB 253 (Climate Corporate Data Accountability Act) and SB 261 (Climate-Related Financial Risk Act). Together, they require large companies doing business in California to disclose greenhouse gas (GHG) emissions and climate-related financial risks.
A follow-on bill, SB 219, passed in 2024, introduced technical adjustments, but the main requirements remain set by SB 253 and SB 261.
For investors, these rules extend beyond California. Any company with significant operations or revenue connected to the state may fall within scope.
Update: CARB has deferred the first SB 253 deadline to 10 November 2026 and published implementation guidance confirming a series of first-cycle reliefs, including no assurance requirement. SB 261 remains enjoined and reporting stays voluntary. A full summary of all updates is provided at the end of this article. (Sept 2026)
1. Scope
SB 253 applies to companies with global revenues above US$1 billion, and SB 261 to those above US$500 million, if doing business in California.
2. Deadlines
SB 253 Scope 1 and 2 reports are due by 10 November 2026 covering 2025 data, deferred from 10 August. Scope 3 reporting begins in 2027. SB 261 reporting is currently voluntary following a Ninth Circuit injunction.
3. Assurance
For SB 253, CARB will accept 2026 submissions with or without limited assurance. Limited assurance is proposed from 2027, moving to reasonable assurance for Scopes 1 and 2 by 2030.
4. CARB clarifications
CARB's board approved the initial regulation in February 2026. CARB withdrew the package from the Office of Administrative Law in June, published modified text in July and has since issued guidance and a voluntary intake platform for the first cycle. Final OAL approval is still outstanding.
5. Investor impact
Asset managers should evaluate portfolio exposure, anticipate disclosure requirements and expect some variability in reporting formats during 2026. Given the breadth of the first-cycle reliefs, investors should expect partial coverage rather than a complete dataset, including companies that file a statement of non-reporting instead of emissions data.
🔹 SB 253 (Emissions Disclosure):
Companies with over US$1 billion in global annual revenue doing business in California must report their full GHG emissions footprint (Scopes 1, 2, and 3).
🔹 SB 261 (Climate-Risk Disclosure):
Companies with over US$500 million in global annual revenue must publish biennial reports on climate-related financial risks and mitigation strategies.
Both public and private companies are covered. Insurance companies are exempt from SB 261.
CARB has published a Preliminary List of Reporting and Covered Entities, identifying approximately 4,000 companies that may fall within scope of SB 253 and SB 261.
📄 Preliminary List of Reporting/Covered Entities (posted 24 September 2025)
The list is non-exhaustive and intended to help organisations assess potential applicability - inclusion does not confirm obligation, and omission does not guarantee exemption.
🔹 SB 253 - Greenhouse Gas (GHG) Emissions Reporting
• Scope 1 and Scope 2 reporting begins with 2025 data, with first reports due by 10 November 2026
• Scope 3 reporting begins with 2026 data, with first reports due in 2027
• Reports must follow the GHG Protocol, the international standard for emissions accounting
• Companies may use CARB’s draft Scope 1 and Scope 2 reporting template (found here), published in October 2025, or another consistent format during the first reporting cycle. The template remains optional. CARB will also accept existing annual reports, data already reported to other programmes or voluntary initiatives, and will not mandate a specific emission factor dataset for 2026
• Independent third-party assurance is phased in. CARB will accept 2026 submissions with or without limited assurance, with limited assurance proposed from 2027 and reasonable assurance by 2030.
• Companies that were neither collecting nor planning to collect Scope 1 and 2 data when CARB issued its 5 December 2024 enforcement notice are not expected to submit emissions data for the first cycle. CARB asks these companies to file a statement of non-reporting on company letterhead.
• Covered entities are assessed a fee whether they submit emissions data or a statement of non-reporting. Under CARB's proposed text, invoices would be issued on or before 10 December 2026 with payment due within 60 days.
🔹 SB 261 - Climate-Related Financial Risk Reporting
• The 1 January 2026 statutory deadline is not being enforced. CARB will set a new date once the Ninth Circuit appeal is resolved.
• Reports must align with TCFD (Task Force on Climate-Related Financial Disclosures) or ISSB (International Sustainability Standards Board) frameworks
• Companies must disclose material physical and transition risks, governance structures and mitigation strategies
🔹 Penalties for Non-Compliance
• SB 253: up to US$500,000 per year
• SB 261: up to US$50,000 per year
• A safe harbour applies for Scope 3 disclosures where companies make reasonable good-faith efforts
• CARB will exercise enforcement discretion in the initial reporting years, focusing on good-faith compliance rather than penalties
The California Air Resources Board (CARB) is responsible for developing the implementing regulations for SB 253 and SB 261.
Recent proposals and workshops have clarified how the rules will apply in practice:
🔹 Revenue thresholds - measured globally
Total annual revenue will be assessed on a global consolidated basis, covering worldwide gross revenue across the consolidated group. This prevents companies from restructuring subsidiaries to avoid reporting thresholds.
🔹 Reporting entity boundaries - parent-level reporting
Consolidated parent-level reporting will generally be permitted if consistent with GAAP or IFRS consolidation. This avoids separate reports for each subsidiary.
🔹 Definition of “doing business in California”
CARB will rely on the California Franchise Tax Board definition, which uses bright-line tests for sales, property, or payroll in California. These thresholds are updated annually.
🔹 Templates and digital submission
On 10 October 2025, CARB published a draft Scope 1 and Scope 2 emissions reporting template for SB 253, open for public comment until 27 October 2025. The template will be voluntary for the first reporting cycle, covering 2025 data due in 2026, and is expected to be finalised later in 2026 as part of the broader rulemaking process.
CARB's board approved the California Greenhouse Gas Reporting and Climate Financial Risk Disclosure Initial Regulation on 26 February 2026. CARB submitted the package to the Office of Administrative Law in May, withdrew it in June to make clarifying changes and deferred the first Scope 1 and Scope 2 deadline from 10 August to 10 November 2026. Modified text was published on 27 July with comment closing on 11 August. The regulation still requires OAL approval, and companies should report to the November date while that process completes.
CARB has confirmed it will apply enforcement discretion during the first cycle, focusing on good-faith compliance rather than penalties. A second rulemaking covering 2027 and beyond is in progress, with a formal draft expected this autumn.
Official CARB resources: CARB Climate Disclosure Rulemaking Page
For a detailed breakdown of these refinements, Danesmead Advisory has provided a useful update on how the CARB's updates are shaping final implementation, which you can read here.
🔹 Scope is global:
Companies outside the US may still be required to comply if they do business in California.
🔹 Alignment with other regimes:
California’s rules are broadly consistent with the EU’s Corporate Sustainability Reporting Directive (CSRD) and the UK’s Sustainability Disclosure Requirements (SDR).
🔹 Portfolio implications:
Scope 3 obligations extend into supply chains, meaning portfolio companies could face indirect reporting pressures.
🔹 Risk assessment:
Investors should consider whether companies in their portfolios are prepared to comply and whether reported data is credible.
🔹 Disclosure quality and comparability:
Early disclosures under SB 253 and SB 261 may vary in format and level of detail until CARB finalises templates in 2026. Investors should monitor how companies adopt the draft reporting framework, as early reporters are likely to set benchmarks for best practice and influence market expectations.
The California disclosure rules reflect a wider shift from voluntary sustainability reporting toward mandatory climate disclosure in the US.
While differences remain between jurisdictions, there is clear momentum toward convergence of ESG reporting requirements across the US, EU, and UK.
For asset managers and hedge funds, this represents both a compliance consideration and a data opportunity. Companies will be expected to provide more consistent, verifiable information - which investors can use to assess risk, inform allocation, and engage with issuers.
The Integrum Platform has already identified 500+ companies with over $1 billion in revenue that fall within scope of California’s climate disclosure laws (SB 253 and SB 261) - a critical blind spot investors cannot afford to ignore.
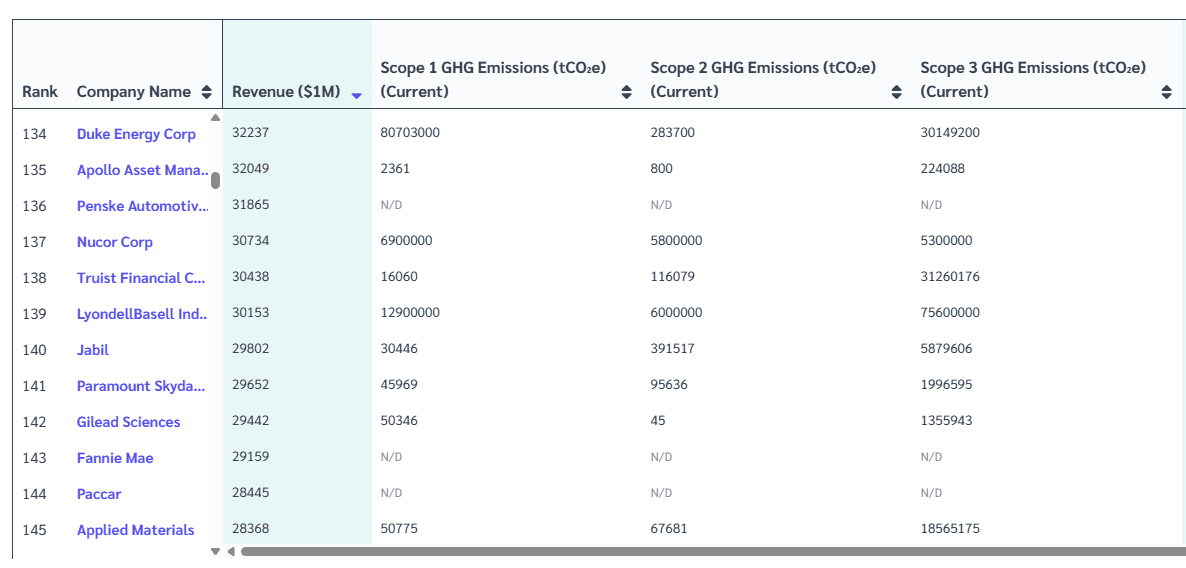
Use our Screening & Reporting solutions to make your SB 253 & SB 261 reporting quick and painless.
ESG Intelligence which is fast, transparent and affordable - only on the Integrum Platform.
CARB has published implementation guidance and opened a voluntary intake platform for the first SB 253 reporting cycle, with initial Scope 1 and Scope 2 reports due 10 November 2026.
• Deadline moved to 10 November 2026: CARB withdrew its regulatory package from the Office of Administrative Law in June 2026 and deferred the first year Scope 1 and Scope 2 deadline by three months from 10 August. Modified text was published on 27 July 2026 with comment closing 11 August. The regulation still requires OAL approval, and companies should report to the November date in the meantime.
• First cycle reliefs confirmed: Companies may report Scope 1 and Scope 2 figures derived from data they already held or were collecting when CARB issued its 5 December 2024 enforcement notice. Companies that were neither collecting nor planning to collect that data are not expected to submit emissions data and should instead file a statement of non reporting on company letterhead.
• No assurance required this cycle: CARB will accept submissions whether or not limited assurance has been obtained. Limited assurance is proposed to apply from 2027.
• Format flexibility: Existing annual reports, data reported to other programmes and CARB's draft template are all acceptable. CARB will not mandate a specific emission factor dataset for 2026.
• Fees apply regardless: Covered entities are assessed a fee whether they submit emissions data or a statement of non reporting, with invoices proposed on or before 10 December 2026 and payment due within 60 days.
• 2027 rules previewed: CARB has confirmed it will phase in Scope 3 by category, starting with purchased goods and services, fuel and energy related activities, waste generated in operations, business travel and employee commuting. A formal draft is expected this autumn with a 45 day comment period. Nothing previewed at the July workshop has been adopted.
• SB 261 remains enjoined: The Ninth Circuit heard oral argument on 9 January 2026 and has not ruled. SB 261 reporting stays voluntary and SB 253 remains in effect.
For investors, 10 November is the point at which the first SB 253 data enters the market. Given the breadth of the first year reliefs, expect thin and inconsistent coverage rather than a clean dataset, including a population of companies that file nothing at all.
Sources:
On 26 February 2026, the California Air Resources Board (CARB) board approved the California Greenhouse Gas Reporting and Climate Financial Risk Disclosure Initial Regulation, completing the rulemaking process under SB 253 and SB 261.
Key developments from the adoption:
• August 10, 2026 deadline confirmed: CARB has set August 10, 2026 as the first-year disclosure deadline for SB 253 Scope 1 and 2 emissions (covering 2025 data). This is the first concrete statutory deadline established under the regulation.
• Scope 3 unchanged: Scope 3 value chain emissions reporting remains mandated from 2027, covering data from the 2026 reporting year.
• SB 261 remains voluntary: Following the Ninth Circuit injunction issued in November 2025, CARB has confirmed that SB 261 climate-risk reporting is currently voluntary. As of the adoption announcement, 120 climate-related financial risk reports had already been voluntarily submitted and made publicly available.
• OAL approval outstanding: Board approval did not conclude the process. The regulation remained subject to review by the Office of Administrative Law.
For investors, the August 10 deadline marks the point at which SB 253 data will begin entering the market. Early variability in reporting formats should be expected while CARB's draft template is tested in practice.Sources:
ESG Today: California Sets August 2026 Deadline for First Corporate Climate Reports
The California Air Resources Board (CARB) has announced several key implementation updates for SB 253 (Climate Corporate Data Accountability Act) and SB 261 (Climate-Related Financial Risk Act):
• Rulemaking delay: The initial rulemaking process has been pushed to Q1 2026, instead of late 2025, to allow for additional stakeholder feedback and technical refinements.
• Draft reporting template: On 10 October 2025, CARB published a draft Scope 1 and Scope 2 emissions reporting template under SB 253. The template is open for public comment until 27 October 2025.
• Voluntary first cycle: Use of the new template will be voluntary for the first reporting cycle (covering 2025 data, due 2026). Companies may submit disclosures in other compliant formats while the template is tested.
• Enforcement discretion: CARB has confirmed it will apply enforcement discretion during the early years, focusing on good-faith compliance efforts rather than penalties.
• Deadlines unchanged: The statutory reporting dates remain the same — SB 261 reports from January 2026 and SB 253 Scope 1 and 2 from 2026 (Scope 3 from 2027).
These updates introduce a phased rollout that will affect how quickly investors gain access to consistent emissions and climate-risk data, but they also reduce compliance risk for companies preparing initial SB 253 and SB 261 disclosures.
Sources:
CARB Climate Disclosure Rulemaking Page
ESG Today: California Delays Rulemaking for New Climate Reporting Regulations
On 18 November 2025, the United States Court of Appeals for the Ninth Circuit issued an injunction halting enforcement of SB 261 (the climate-related financial risk disclosure law) pending the outcome of appeals.
The decision did not pause SB 253 (the greenhouse-gas emissions disclosure law); enforcement of SB 253 remains on course.
According to the ruling, covered entities are no longer required, for the time being, to submit the biennial climate-risk reports mandated by SB 261, though they should continue preparations and monitor further regulatory developments.
Sources:
California Corporate Climate Disclosures Partially Enjoined - Ropes & Gray
Browse frequently asked questions about the platform.
Can’t find the answer you’re looking for? Please get in touch with our team.